
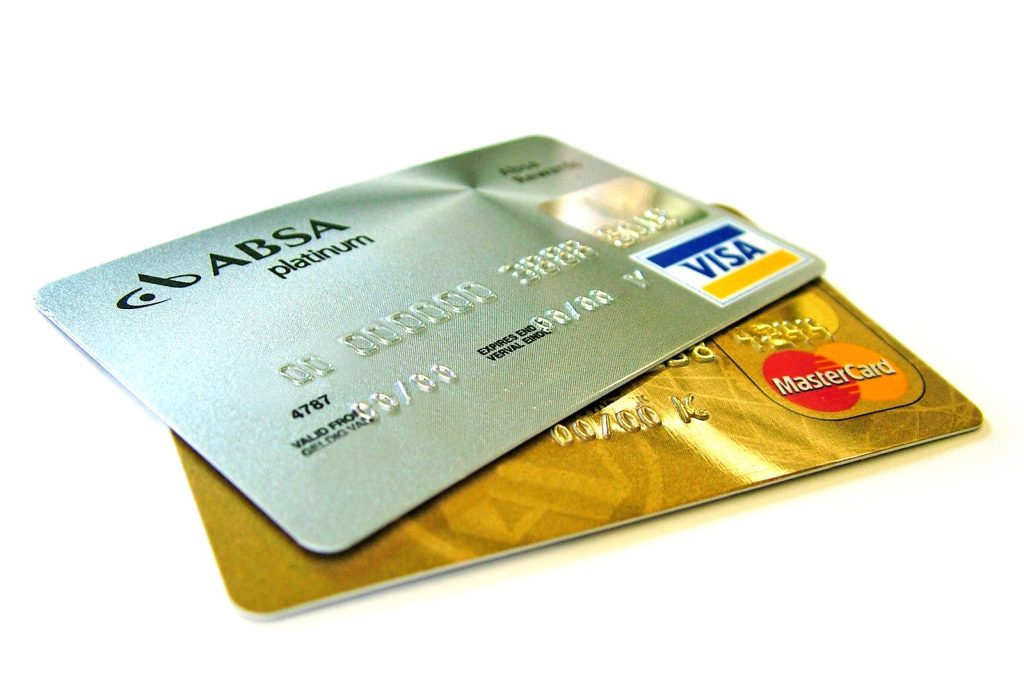
NEW YORK — The math on a secured credit card is brutal and simple. You hand over cash — a few hundred dollars — and the bank hands back a credit line of exactly that amount. For months or a year, you borrow your own money and pay it back.
Then the deposit returns. The credit bureaus have watched the whole time.
That’s the entry point for a graduate with no credit history. No trust fund required. No perfect job offer needed.
Just a deposit that sits in the bank’s hands as collateral. The system works because it forces responsibility.
Miss a payment and the bank keeps the cash. Make every payment on time and the deposit comes back, along with a credit score that has started to grow. The human side of this is about opportunity, not just numbers.
A decent apartment rental, a car loan, even some jobs — all of them now require a credit check. The fresh graduate staring down student loan statements sees a credit card as more trouble. The reality is different.
Used the right way, that card unlocks things. There is another route that gets less attention.
Becoming an authorized user on someone else’s card. No separate application. No credit check.
The card’s payment history gets reported to the credit bureaus under your name as well. But the catch matters for families.
You are responsible for whatever charges you make. Miss a payment and it damages both your credit score and the primary cardholder’s. Shared responsibility, not a free ride.
If no one is willing to add you as an authorized user, that is fine. It is not necessary. The secured card path works alone.
Patience is the real requirement. Building credit takes time — weeks won’t do it.
A few months won’t do it. This is a slow process, and the people who succeed are the ones who accept that. The forces behind this are straightforward.
Lenders want proof that you can handle debt before they lend you money. The credit bureaus exist to provide that proof.
A young person with no history is invisible to the system. The secured card makes them visible. The authorized user route borrows someone else’s visibility.
Both methods work because they produce a track record. Where this is likely to lead is also straightforward. The graduate who builds credit responsibly over a year or two will qualify for better cards.
Cards with rewards. Cards with travel benefits.
Free flights down the road become possible. The same person who could not rent an apartment at age 22 can get a mortgage at age 30. The path is clear.
But there is a trap. The same card that builds credit can destroy it.
A single missed payment, a balance that grows too large, a late fee that spirals — all of it shows up on the credit report. The system rewards consistency and punishes mistakes. The fresh graduate has to understand that before signing up.
The families watching their kids take those first wobbly steps into financial independence have a role too. They can explain the rules. They can model responsible use.
They can decide whether to add a child as an authorized user, knowing the shared risk. The trust fund and the perfect job offer are not required.
A few hundred dollars as a deposit and a willingness to wait are enough.




