
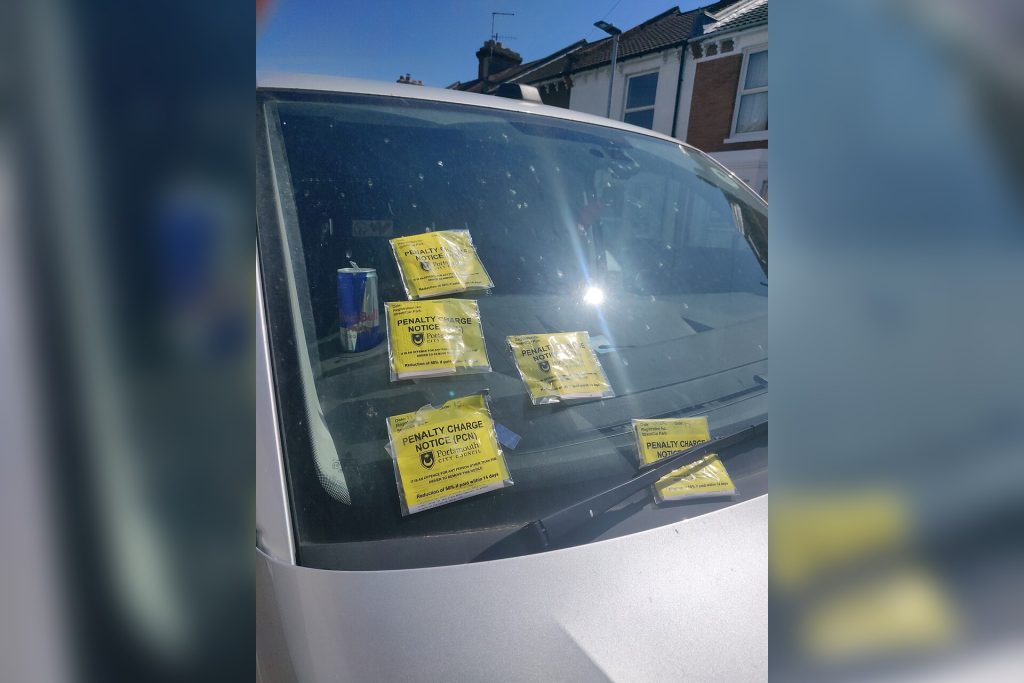
A £60 parking ticket. Refused on principle, left alone, and a few months later it sits on a credit file as a County Court Judgement. Jamie Elvin, a director at the London broker Strive Mortgages, says that is how some borrowers lock themselves out of high street lending.
Elvin’s firm specialises in mortgages for self-employed people and sole traders. He told the Mirror and the Express that his clients rarely see the chain coming. “People simply don’t join the dots when they are taking a stand over a small fine or unpaid debt,” he said. “They don’t understand how quickly, if left unresolved, it can impact their mortgage.”
His sums are blunt. “A parking fine may only be £60, but if you refuse to pay it for whatever reason, that blip on your credit score could cost you six thousand pounds in additional interest if high street lenders will no longer take you on.” The same warning applies to a disputed mobile phone bill that grows into a CCJ.
How lenders read it
To an underwriter, the argument over who was right does not exist. Elvin said borrowers must understand that a lender reads numbers, not the rights and wrongs of a quarrel. Once an unpaid charge becomes a default or a CCJ, it registers as plain adverse credit. Fewer lenders will touch the file, the rate climbs, or the application is turned down.
He called it ironic that someone with a strong income and significant assets can end up paying extra for years over a small sum they refused to hand over. Even when a mortgage does come through, he said, it will often cost more, because the lenders willing to take such a file are usually specialist firms, not the big banks on the high street.
His advice is to pay first and fight afterwards. “If a bill is wrong, pay it and then challenge it properly. Do not ignore it, because lenders are far less interested in who was right than whether the debt was left unresolved.”
The ticket you never saw
Elvin raised a second trap that has nothing to do with principle. People move house and do not arrange for their post to be redirected, a step he said is widely recommended for half a year or even twelve months. They also leave their driving licence and vehicle logbook at the old address. A speeding ticket or parking charge then goes unseen, escalates, and ends up as a default or CCJ the owner never knew about.
The problem tends to surface only at remortgage time, when the judgement turns up on the credit file. Elvin described this as possibly the commonest error on the mortgage side, and said a minor dispute can end up costing far more than it should.
Sources
- £60 parking fine could wreck your mortgage chances, warns broker – The Mirror
- Ignoring a £60 parking fine 'could cost you your home' | Personal Finance | Finance | Express.co.uk




