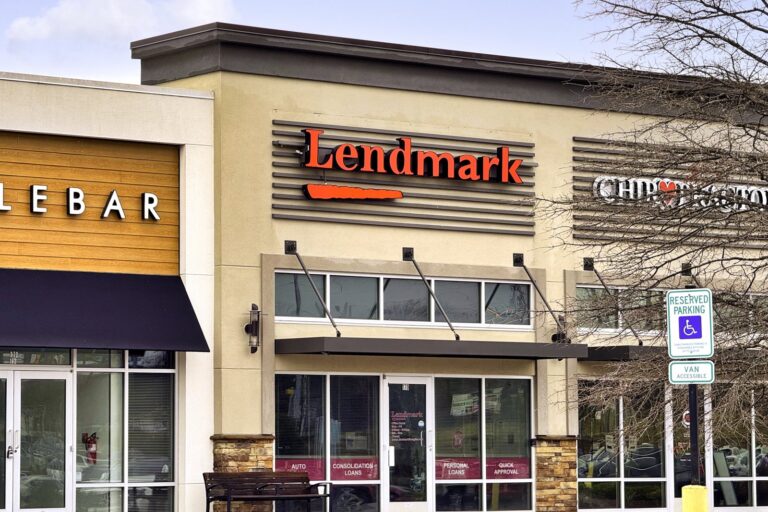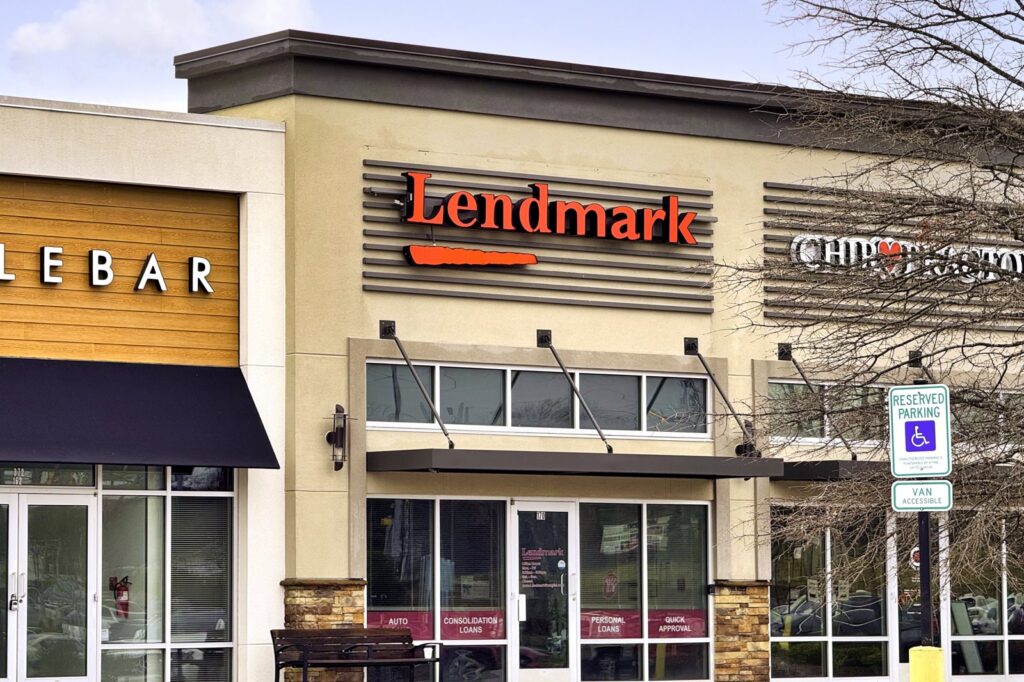
LAWRENCEVILLE, GA., October 29, 2026 — Lendmark Financial Services opened three new branches this week in Port Orange, Fla., Greenville, S.C., and Campbellsville, Ky., pushing its national network to approximately 560 locations across 24 states. The expansion adds to a footprint that now includes 13 branches in Florida, 24 in South Carolina and 26 in Kentucky.
The Strategy Behind Regional Branch Expansion
Lendmark has grown steadily since its founding in 1996, building a network that now employs 2,300 people nationwide. Headquartered in Lawrenceville, Ga., the company operates in the consumer finance space, providing personal credit and loan solutions directly to borrowers. According to the company, the latest branch openings represent a continued push to deepen its presence in the Southeast rather than chase broad national scale.
Executive Vice President of Branch Operations E.J. Ryan said the additions are meant to increase access to financial solutions in communities that need them most. The company frames the strategy as ensuring customers have a local team for support through both planned and unplanned life events. By the numbers, the three new locations bring the firm’s total branch count to roughly 560, a figure that positions it well below the approximately 1,500 branches operated by larger competitor OneMain Financial as of late 2020.
The new addresses are 3751 Clyde Morris Blvd., Unit 5 in Port Orange; 5000 Old Buncombe Road, Suite 54 in Greenville; and 399 Campbellsville Bypass, Suite 1500 in Campbellsville. Each site is staffed to handle consumer loan origination and servicing on site, a model the company says differentiates it from online-only lenders.
How Lendmark Serves Local Consumers and Small Businesses
The core retail business centers on personal loans for consumers across its 24-state footprint. In addition, Lendmark provides sales financial services for nearly 25,000 retailers and independent auto dealerships. This indirect lending channel allows the company to finance purchases at the point of sale, particularly for used vehicles sold by smaller dealerships that may not have captive finance arms.
For borrowers, the product set is designed to address both planned expenses and emergency needs. The company states it strives to offer stability through affordable loan offerings, though specific rate ranges and underwriting criteria were not disclosed in the announcement. The bottom line: the branch network acts as the primary interface for origination, payment collection and customer service, keeping decision-making local rather than centralized in a call center.
Investors will note that the indirect auto and retail partner count of nearly 25,000 represents a significant distribution channel that complements the branch footprint. This dual-channel approach — direct-to-consumer branches plus point-of-sale financing — mirrors the structure of larger peers but on a more regional scale.
The Role of Personalized Service in Community Lending
Lendmark emphasizes that its approximately 560 branches deliver personalized service with every transaction. The new locations in Florida, South Carolina and Kentucky are staffed by local teams authorized to make lending decisions and manage accounts through the life of the loan. This model contrasts with digital-first lenders that rely on algorithmic underwriting and centralized servicing.
The company’s growth trajectory since 1996 has been built on this physical presence. While fintech competitors have scaled without branches, Lendmark has maintained that face-to-face interaction matters for the credit profile it serves. The figure that matters here is the branch count relative to population centers in the Southeast, where the company has concentrated its recent growth.
Ryan’s statement highlighted that the expansion is about more than footprint; it is about ensuring a local team is available for financial support. In practice, this means branch managers and loan officers handle modifications, hardship arrangements and payoff discussions in person, a capability the company views as a competitive advantage in its target markets.
Corporate Social Responsibility Through the Climb to Cure Initiative
Alongside lending operations, Lendmark runs a signature charitable program called Climb to Cure in partnership with CURE Childhood Cancer, an Atlanta-based nonprofit. Since the partnership began, the company has raised over $12.4 million for the organization. Funds support targeted pediatric cancer research at institutions nationwide and provide resources to families navigating childhood cancer treatment.
The mechanism is straightforward: customers can donate $1 when closing a loan at eligible branch locations, and Lendmark matches the donation. The program is not available in South Carolina due to state regulations. The initiative ties the company’s core transaction volume — loan closings — directly to its philanthropic output, creating a recurring revenue stream for the charity tied to business activity.
CURE Childhood Cancer focuses on ensuring every family gets support and every child receives care. The $12.4 million raised places Lendmark among the nonprofit’s significant corporate partners. For a company of 2,300 employees and 560 branches, the fundraising total reflects sustained engagement over multiple years rather than a one-time campaign.
Growth Trajectory Since 1996
Founded in 1996, Lendmark has expanded from a single Georgia location to a coast-to-coast network of approximately 560 branches. The company remained privately held through its growth phase, avoiding the public market volatility that affected some peers during the 2008 financial crisis and subsequent regulatory shifts. Its headquarters remain in Lawrenceville, where the executive team oversees branch operations, the indirect lending division and the Climb to Cure partnership.
The Southeast focus is evident in the state-level totals: 13 branches in Florida, 24 in South Carolina and 26 in Kentucky after this week’s additions. These three states alone account for 63 locations, or roughly 11 percent of the national network. The concentration suggests a strategy of density over breadth, building market share in contiguous states where brand recognition and operational logistics create efficiencies.
With 2,300 employees servicing the network, the average branch runs lean, typically staffed by a handful of loan officers and a manager. This structure has allowed the company to maintain physical presence in smaller communities like Campbellsville, Ky., and Port Orange, Fla., where larger banks have consolidated branches. The history since 1996 shows a lender that grew by filling gaps left by traditional banks retreating from small-dollar consumer lending in non-urban markets.
Sources
- Lendmark Financial Services Expands its Southeast Presence with New Branches in Florida, South Carolina and Kentucky
- OneMain Financial
- Lendmark Financial Services Expands its Southeast Presence with New Branches in Florida, South Carolina and Kentucky
Photo: Harrison Keely (CC BY 4.0)