
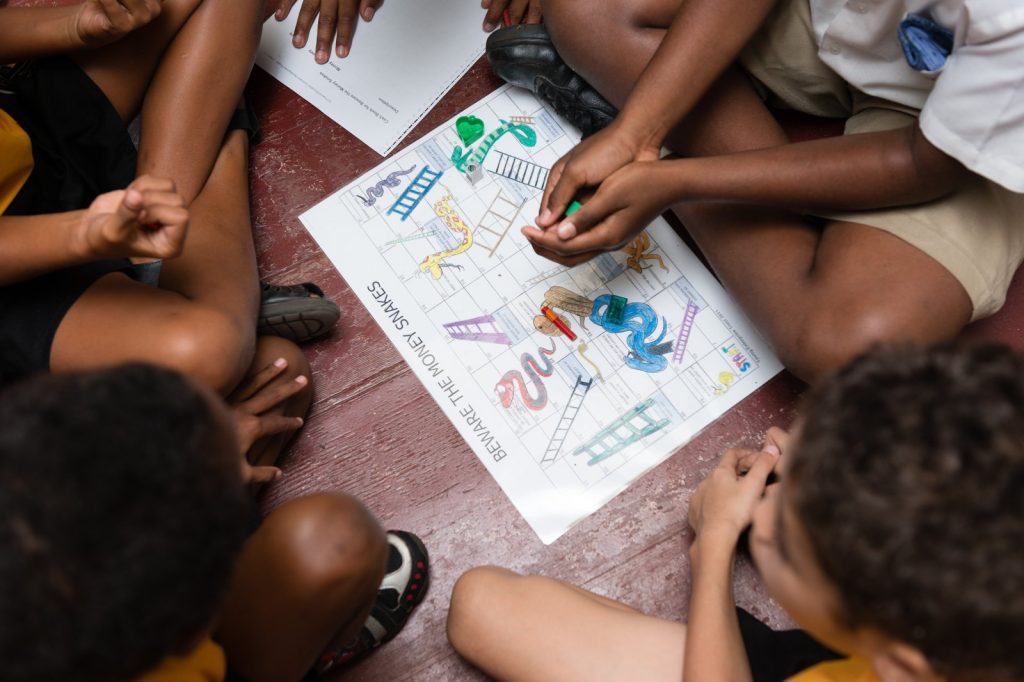
Gaps in financial education persist across many regions, leaving young people without practical money management skills that formal schooling often overlooks. A new online programme, targeting children aged nine to 15, now seeks to fill that void through a series of live, expert-led sessions conducted via Zoom. Organisers say the curriculum moves beyond theoretical economics to address real-world lessons in earning, saving, smart spending, and building wealth early.
A Four-Session Digital Curriculum
The course consists of four sessions, each lasting 120 minutes, and covers a range of topics aimed at equipping children with foundational financial knowledge. Among the specific areas of instruction is UPI safety, a digital payment system that has become widely used across the Indian subcontinent and is increasingly relevant among diaspora communities.
Participants who complete the programme will receive a digital certificate, a credential designed to serve both as a motivator and as a record of learning. According to promotional materials, the programme is designed to be engaging and age-appropriate, helping children understand how money works through interactive instruction. The organisers have stressed that the lessons are delivered live, allowing for direct interaction between instructors and students.
The programme is being advertised through the Times of India, one of the country’s largest English-language newspapers, which recently updated its privacy and cookie policies to comply with new European Union data regulations. The newspaper has asked users to review and accept these changes to continue accessing its website.
This is not the first such initiative to emerge from the region. Financial literacy programmes for youth have gained traction in recent years, particularly in urban centres where digital payments and online commerce are expanding rapidly. The inclusion of UPI safety reflects a broader recognition that children need to navigate digital financial tools safely from an early age.
Why Financial Literacy Matters Now
The programme comes at a time when children are encountering financial decisions earlier than previous generations did, driven in part by the rapid spread of digital payment systems across regions including the Indian subcontinent and the Middle East. Financial literacy — defined as the ability to understand and effectively use money management skills such as earning, saving, budgeting, and investing — is associated with better financial decisions and lower costs when borrowing.
Individuals who lack such knowledge often struggle to plan for the future and may pay more for debt. Governments began paying serious attention to financial education in the early 2000s. In 2003, the Organisation for Economic Co-operation and Development launched an inter-governmental project to improve financial literacy standards worldwide.
That same year, the United Kingdom started a national strategy on financial capability through its Financial Services Authority, and the United States established its Financial Literacy and Education Commission. These efforts were driven by the recognition that formal schooling rarely covered practical money skills.
Despite such initiatives, many education systems in the Middle East and South Asia still do not include practical money management in their standard curricula, leaving a gap that programmes like this one aim to address.
Targeting a Critical Age Group
Observers of financial education trends note that programmes targeting children aged nine to 15 are particularly valuable. This age group is developmentally ready to grasp abstract concepts such as compound interest and budgeting, yet young enough to form lasting habits. The digital certificate offered upon completion may also serve as an additional motivator for participants, providing a tangible outcome for their effort.
The organisers have not disclosed enrollment numbers or pricing details, but the programme’s availability through a major news platform suggests a significant marketing push. What remains to be seen is how widely such programmes will be adopted, particularly in regions where financial literacy is not yet a priority in formal education systems.
For now, the course represents one more option for parents seeking to equip their children with practical skills that schools often overlook. Whether it will succeed in bridging the financial literacy gap will depend on how many families choose to enrol and how effectively the lessons translate into real-world behaviour.




