
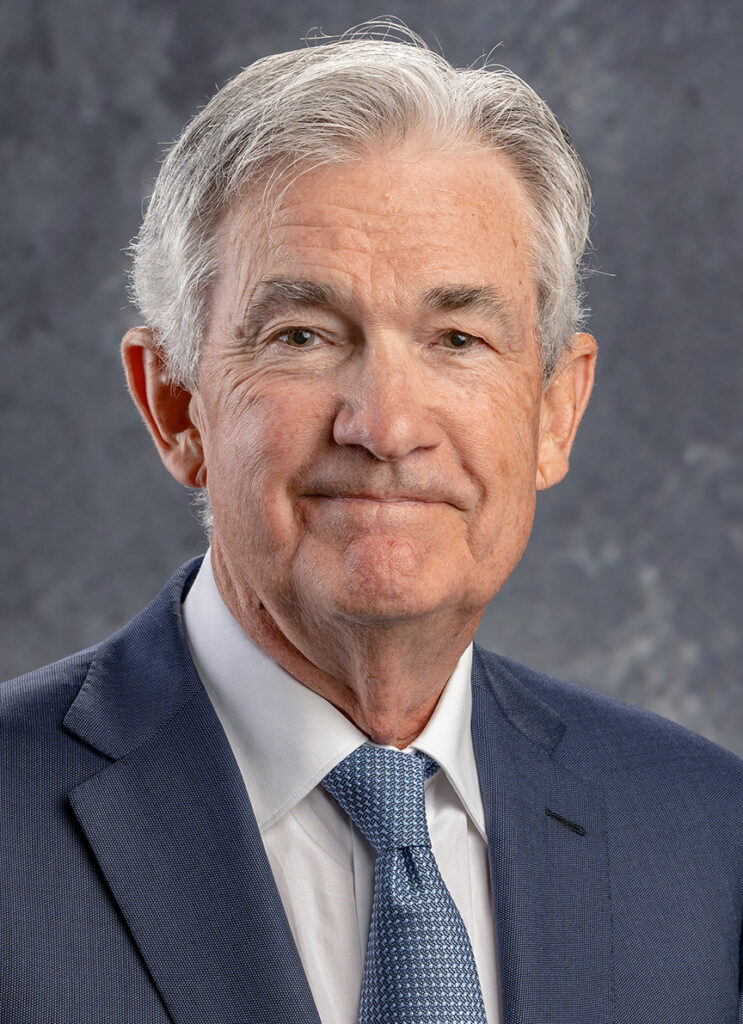
WASHINGTON, July 5 — The Federal Reserve finds itself in a holding pattern, with interest rates steady and the central bank’s leadership insisting on a data-dependent approach before any shift in policy. Chair Jerome Powell has emphasised that every move will be guided by incoming economic figures, a stance that has become the defining feature of the current monetary landscape. The Fed’s primary tool, the federal funds rate, remains in the range set after the most aggressive tightening cycle since the 1980s.
Rates were lifted from near zero in March 2022 to 5.25%-5.50% by July 2023, a rapid ascent designed to wrestle down inflation that had surged across the economy. Under the hood, the technical reality is that borrowing costs across the board are still being shaped by that earlier series of hikes.
The Federal Open Market Committee, which meets eight times per year to set policy, has held rates steady through 2026 so far. Its latest projections, released earlier this year, indicate potential rate cuts if inflation continues to decline toward the 2% target. The detail that matters is the dual mandate.
Codified in the Federal Reserve Act of 1977, the central bank is tasked with promoting maximum employment and stable prices. That twin objective has guided every decision since, and it remains the framework within which the FOMC operates today.
Beyond the rate decision, the Fed has been quietly reducing its footprint in bond markets. Quantitative tightening has trimmed the central bank’s balance sheet from a peak of $9 trillion in 2022 to about $7 trillion as of 2026. That is a substantial unwinding, though the process has been gradual and carefully calibrated to avoid disrupting financial conditions.
The Fed was established in 1913 as the central bank of the United States. More than a century later, its core function remains the same: conducting monetary policy to promote maximum employment and stable prices. The tools have evolved, but the mission has not.
As ever, the question for markets is timing. The FOMC’s 2026 projections point toward rate cuts, but only if inflation keeps moving in the right direction.
Chair Powell has given no firm timeline, and the committee has made clear it will not be rushed. The data will decide, and the data, for now, is not yet conclusive. What to watch next is the inflation trajectory.
If the trend toward the 2% target holds, the Fed may have room to ease. If it stalls, the current steady stance could persist well into the second half of the year.
Either way, the central bank is in no hurry to signal its next move.




