
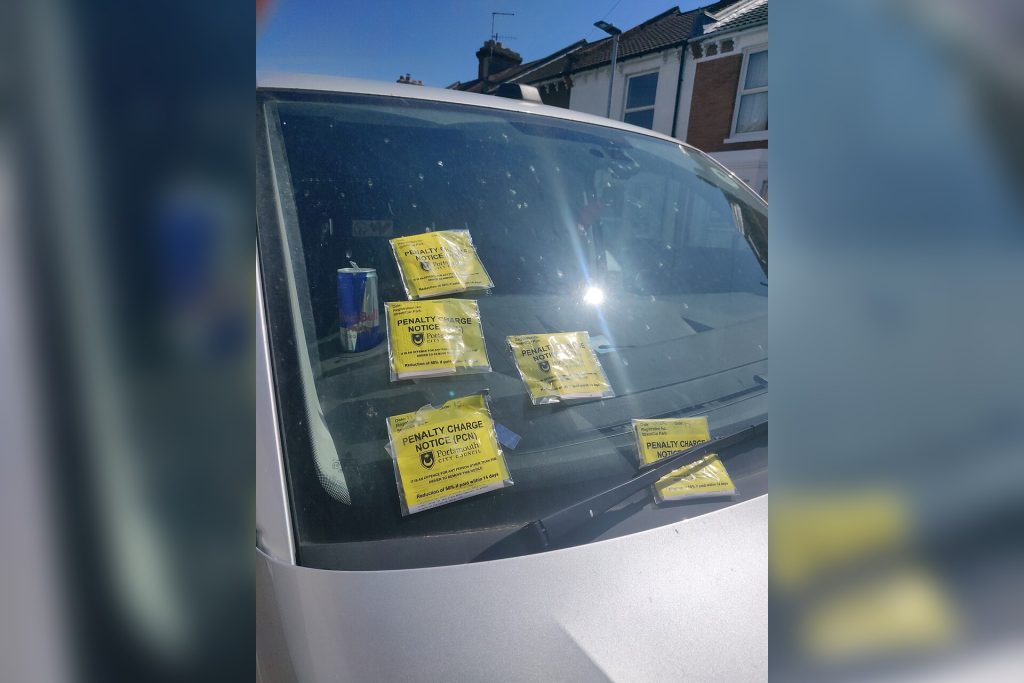
County Court Judgements are binary things. You have one, or you don’t. Lenders do not care how you got it.
A new warning from a London mortgage broker makes that plain: a single unpaid parking fine, left to fester, can lock a borrower out of the high street entirely. Jamie Elvin, director of Strive Mortgages, which works with self-employed clients, said the disconnect is routine.
People see a £60 ticket as unjust. They refuse to pay on principle. The fine escalates.
A default appears on credit files. Then a CCJ.
At that point, the moral argument is dead. Lenders see only a black mark. “They don’t understand how quickly, if left unresolved, it can impact their mortgage,” Elvin said.
The policy question here is blunt. Should credit reporting give any weight to context? Right now, it does not.
A disputed charge, a genuine error, a principled refusal — all look the same to an automated underwriting system. The data is the data.
No notes allowed. Elvin calculated the real cost. A single blip from a minor fine could add £6,000 in extra interest.
That is the penalty for being shut out of high street rates. Someone with strong income and significant assets ends up paying more for years because they took a stand over a comparatively small amount.
The irony is not lost on him. “Lenders only see the data rather than the right and wrongs of a dispute,” he said. There is no regulatory push to change this.
The Financial Conduct Authority has not signalled any move to force lenders to weigh the story behind a default. The system is designed for speed and consistency. A human review of every adverse entry would slow mortgage approvals to a crawl.
So the rule stays: pay the fine, even if you think it is wrong. The numbers back the warning.
A £60 parking fine, left unpaid, triggers a default. That default shows up on credit data as adverse credit — no context, no explanation, no room for the righteousness of your dispute. Lenders do not want to be judges of fairness.
They are data processors. “Once an unpaid parking fine or bill turns into a default or CCJ, all that they see is black and white adverse credit,” Elvin said.
What changes? Nothing, unless the borrower acts. The policy is fixed.
The only variable is whether the person pays the fine before it escalates. That is the choice. Not whether the fine was fair.
Whether you want a mortgage. Elvin’s firm specialises in self-employed and sole trader mortgages.
Those borrowers often have irregular income and less straightforward credit histories. They are already closer to the edge. A single CCJ can tip them into a specialist lender market where rates are higher and terms tighter.
The trend underneath is a mismatch between personal principles and financial reality. People see a fine as unjust and refuse to pay it on moral grounds.
But lenders are not arbiters of fairness — they are data processors. That data can mean fewer lenders willing to offer a mortgage at all. The advice is simple, if unsatisfying.
Pay the fine. Dispute it later if you must. But do not let it become a CCJ.
The system will not bend for your principles. It will just charge you £6,000 more.




